


No, in the majority of cases, boarding school fees are not directly tax-deductible. Everything depends on your tax residence, not the country where the school is located: France applies a symbolic flat-rate reduction, Switzerland and the United Kingdom offer almost no benefit to foreign families, and the United States excludes private K-12 schooling from the standard tax framework. It is better to integrate the total cost into your budget rather than count on tax relief.
Why the deductibility of boarding school fees depends on your tax residence, not the country of the school
This is a common misunderstanding among international families: assuming that the applicable tax system is that of the country where the boarding school is located. In reality, it is the parents’ tax domicile that determines the applicable regime, regardless of the location of the institution, whether in Switzerland, the United Kingdom, or elsewhere.
Another distinction deserves to be made. Certain European legislations separate tuition fees (courses, educational supervision) from childcare expenses (accommodation, supervision outside school hours). This nuance matters: several tax provisions target only childcare for young children, not boarding school education for adolescents.
To put the issue in context, it is better to know in advance the average annual budget for a boarding school in Switzerland before evaluating a potential tax deduction.
Expatriate families with dual tax residence must exercise particular caution. A double taxation treaty between two states can significantly modify the treatment of tuition fees, hence the importance of verifying this point before enrollment rather than during the school year.
The taxation of boarding school fees in France, Belgium, and Luxembourg
France: tax credit and boarding school tuition fees
In France, a tax credit exists for children enrolled in middle school, high school, or higher education. It is a flat rate and does not depend on actual expenses incurred: its amount varies according to the educational level, with no distinction related to boarding or day school status.
Accommodation expenses specific to boarding schools receive no specific benefit: this flat-rate amount remains identical whether a child is a day student or a boarder at a high-end Swiss boarding school, and represents a symbolic fraction of the actual cost of schooling. For a French family living abroad and enrolling their child outside France, the question becomes more complex: the loss of French tax resident status may result in the loss of this reduction, depending on the situation.
Belgium and Luxembourg: provisions for childcare expenses
Belgium provides a deduction for childcare expenses, generally capped and reserved for children below a certain age. Luxembourg has a comparable mechanism, also oriented toward childcare rather than international schooling.
In both cases, these provisions rarely, and never fully, cover the fees of a high-end international boarding school. They concern primarily traditional childcare structures (nurseries, after-school care) rather than boarding schools accommodating adolescents.
Switzerland, United Kingdom, United States: regimes unfavorable to international families
In Switzerland, there is no federal deduction for private tuition fees as such. A deduction exists for third-party childcare expenses, but it primarily targets young children and is addressed to Swiss resident taxpayers, which effectively excludes most foreign families enrolling their child in Switzerland without residing there themselves.
In the United Kingdom, there is also no direct deduction for private tuition fees. Only specific structures, such as family trusts allowing the child to benefit from their own tax allowance, are sometimes used by high-net-worth families to optimize the payment of school fees.
In the United States, the tax administration does not allow the deduction of private K-12 tuition fees under the general framework. Certain education savings accounts offer limited flexibility, but international boarding school fees remain outside the scope of standard tax benefits.
For expatriate families, the practical consequence is straightforward: it is better to anticipate the absence of tax benefits and integrate the total cost of schooling into budget planning, rather than rely on hypothetical relief.
This observation sheds light on the profile of families who make up the daily life of certain international boarding schools. Institut Monte Rosa, for example, welcomes co-educational students aged 8 to 19 within an international boarding school offering an American High School track, British A-Levels, and a Swiss program, in a family atmosphere with small class sizes. American, British, or non-resident Swiss families who enroll their children there are precisely those affected by the absence of deductions in their country of origin, which makes realistic budget planning useful from the time of enrollment.
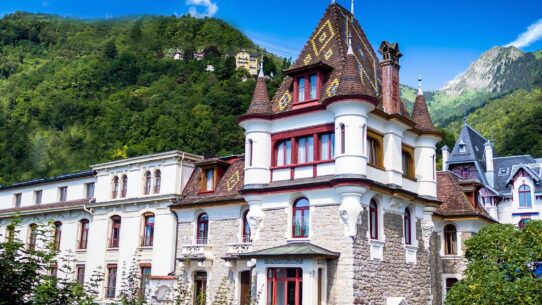
Institut Monte Rosa
Legally optimizing the tax cost of boarding school without crossing the line
No shortcut replaces personalized tax advice. The following avenues are general considerations, to be systematically validated with a professional before any decision.
- Clarify your tax residence status before enrollment, rather than during the school year
- Verify whether the employer, as part of an expatriation package, covers all or part of tuition fees
- Examine, for very high-net-worth families, the value of trust-type structures for the payment of fees
- Systematically retain invoices and enrollment contracts, useful in case of subsequent change in tax residence
These mechanisms do not apply to all situations and require support from an international tax specialist experienced in expatriate family mobility, rather than hasty generalization from isolated cases.
Certain families structure their financial planning well in advance of enrollment, particularly when they are considering long-term international education for their daughters. Surval Montreux illustrates this profile: this exclusively female institute emphasizes international education and leadership development in young women, with preparation for IGCSEs, A-Levels, and the American High School Diploma. The families concerned are often multi-jurisdictional, which makes the question of deductibility variable depending on the country of origin and justifies advance tax planning rather than late reflection.
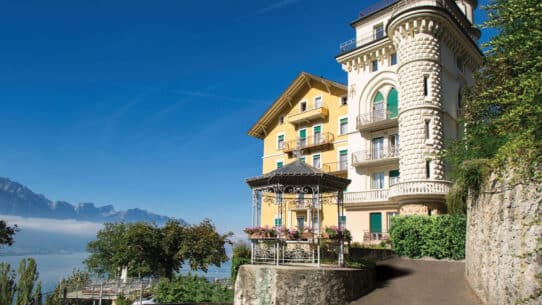
Surval Montreux
Once the budgetary framework is established, the reflection can broaden: to position boarding school among available educational options, it is better to weigh the pros and cons of boarding school before committing for several years.
Special case of multi-resident families and double taxation
On the Vaud Riviera, one scenario recurs regularly: parents who work in one country, a child enrolled in school in Switzerland, and tax residence declared in a third country. This configuration multiplies fiscal gray areas.
Bilateral double taxation treaties play a determining role in defining the regime applicable to tuition fees and, more broadly, to household income. Each treaty has its own criteria for tax attachment, which makes any generalization risky.
The practical recommendation remains constant: request a tax ruling or preliminary consultation before the start of the school year, particularly in case of a change in resident status along the way. The school itself, Swiss or otherwise, does not provide tax advice: only a qualified professional can rule on the situation of a given family. Swiss tax authorities moreover publish official recommendations relating to family taxation, a useful starting point before any specialized consultation.
For families still in the reflection phase regarding the choice of an institution, comparing options remains a logical step once the tax implications are understood. The list of private boarding schools in French-speaking Switzerland allows this choice to be refined with full knowledge of the facts, budget and taxation included.